

Quick Summary:
Standard homeowners insurance generally does not
cover flood damage, including damage caused by rising water or storm surge. Flood insurance is a separate policy, and the difference has left thousands of Louisiana homeowners facing major out-of-pocket losses after Hurricane Katrina, Hurricane Ida, and the 2016 Louisiana floods. For homeowners in Kenner, Jefferson Parish, and the Greater New Orleans area, understanding which policy responds before a storm is essential.
At Harris General Insurance Agency, one of the most common questions we hear is: “Does my homeowners policy cover flooding?” The answer is usually no. Homeowners insurance and flood insurance are designed to protect against different risks, and having one does not mean you automatically have the other.
What Homeowners Insurance Typically Covers
Homeowners Insurance is designed to protect your home and belongings from many sudden, accidental losses. The exact protection depends on your policy, endorsements, deductibles, and limits, but a standard policy commonly includes coverage for:
- Fire and smoke damage
- Theft and vandalism
- Wind and hail damage, subject to the policy’s terms and hurricane or wind deductibles
- Falling objects and certain types of water damage from inside the home
- Personal liability if someone is injured on your property or you cause damage to someone else’s property
- Additional living expenses when a covered loss makes your home temporarily unlivable
Those are important protections, but a homeowners policy also has important exclusions. The biggest one for Louisiana property owners is flood.
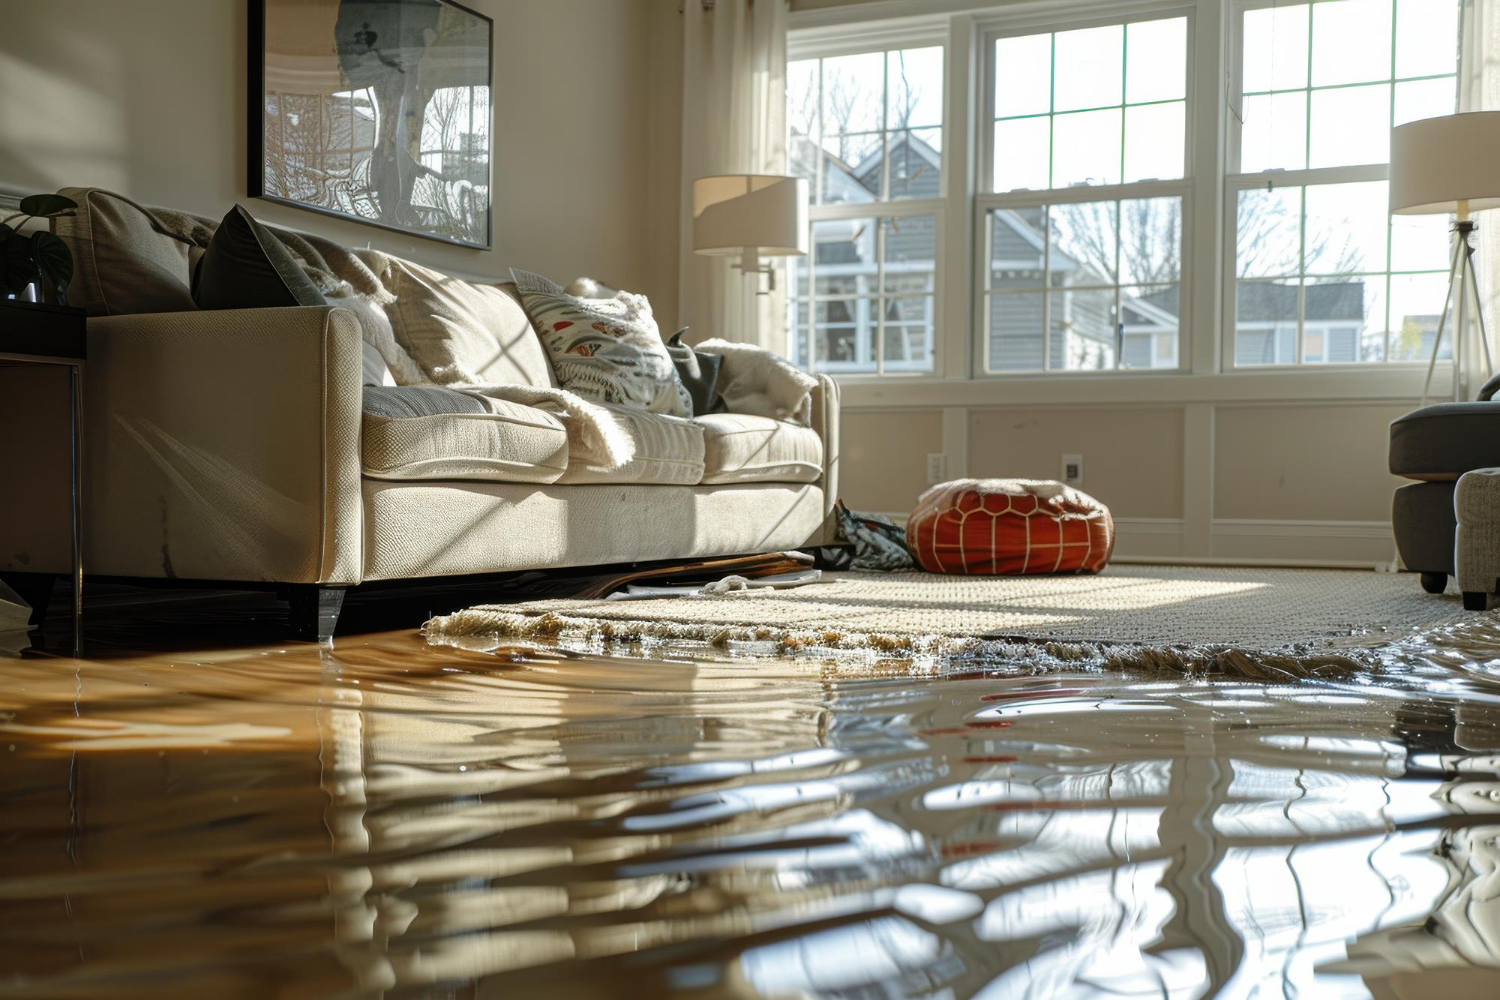
If water enters your home because water has accumulated on the ground, a canal or drainage system overflows, heavy rain causes widespread surface-water flooding, or storm surge pushes water inland, the resulting damage is generally treated as a flood loss. Standard homeowners insurance policies also typically exclude storm-surge losses because storm surge falls within the policy definition of flood. A hurricane can cause both wind damage and flood damage at the same property, which means two different policies may be needed for one event.
What Flood Insurance Covers
Flood Insurance
is separate coverage for physical losses caused by a qualifying flood event. In plain language, it is intended to help when water from outside your home damages the structure, your belongings, or both.
Flood coverage is available through the National Flood Insurance Program (NFIP) and, for qualifying properties, through private flood carriers. Policies can generally provide separate coverage for the building and for personal contents. Depending on the policy selected, covered building items may include the foundation, electrical and plumbing systems, HVAC equipment, built-in appliances, cabinets, flooring, and other permanently installed features. Contents coverage can help protect eligible personal belongings such as furniture, clothing, electronics, and appliances.
Flood insurance is not identical from one policy to another. Coverage limits, deductibles, exclusions, waiting periods, and options for temporary living expenses can vary. An NFIP policy and a private flood policy may be structured differently, so it is important to compare the options based on your property, mortgage requirements, budget, and desired protection.
Why the Difference Matters in Kenner and Jefferson Parish
Flood risk is not limited to homes directly next to a bayou, lake, or canal. Kenner, Jefferson Parish, and the Greater New Orleans area are low-lying communities where intense rain, drainage issues, coastal weather, and hurricane conditions can create serious flood exposure. Even a property outside a high-risk flood zone can experience damaging water during a major rain event.
Local planning data has reported more than 11,000 flood insurance policies in force in Kenner, underscoring how seriously many residents take the risk. Yet local data also shows that many structures remain uninsured for flood. That coverage gap matters because homeowners policies—and commercial multi-peril policies—typically exclude flood losses.
For example, wind may damage a roof during a hurricane, while rising water damages flooring, walls, appliances, and furniture. The wind portion may fall under homeowners insurance if it is covered by the policy. The water damage from flooding may require flood insurance. Without separate flood coverage, a homeowner could have a valid homeowners claim for one part of the loss but no coverage for another costly part.
Kenner’s Community Rating System Discount
Kenner participates in the NFIP’s Community Rating System (CRS), a program that recognizes communities for floodplain management and flood-risk-reduction work that goes beyond minimum requirements. Kenner’s Class 6 CRS rating can provide eligible NFIP policyholders with a 20% premium discount.
This is meaningful savings for Kenner residents, but it does not replace the need to select appropriate building and contents limits. A discount makes protection more affordable; it does not make an underinsured policy sufficient after a major loss. Harris General Insurance Agency can help you review whether your current limits reflect the cost to repair your home and replace the belongings you want protected.
Do Not Overlook the 30-Day Waiting Period
Timing matters. In most cases, an NFIP flood policy has a 30-day waiting period
between purchase and the date coverage becomes effective. There are limited exceptions, such as certain mortgage-related transactions, but homeowners should not assume they can purchase coverage once a storm has been named or rain is already in the forecast.
Waiting until hurricane season is underway—or until a tropical system is approaching the Gulf—can leave you without protection when you need it most. The better time to discuss flood insurance is while the weather is calm and you have time to evaluate options carefully.
Private Flood Insurance May Be an Option
Private flood insurance can be a strong alternative or supplement for qualifying Louisiana properties. Depending on the carrier and property, it may offer different limits, deductibles, underwriting requirements, policy features, and pricing than an NFIP policy. Some private policies may offer higher available limits or broader features, while others may not be the right fit for a particular home or lender requirement.
That is why a side-by-side review is valuable. Harris General Insurance Agency can help homeowners in Kenner, Jefferson Parish, and the Greater New Orleans area understand their NFIP and private flood insurance options—without assuming one solution is right for every property.
FAQ
Does homeowners insurance cover flooding in Louisiana?
Usually no. Standard homeowners insurance generally excludes flood damage, including damage from rising water, surface water, and storm surge.
Does flood insurance cover hurricane damage?
It can cover flood damage caused by a hurricane, such as storm surge or rain-driven flooding. Wind damage is generally handled separately under homeowners insurance if covered.
Do I need flood insurance if I am in a low-risk zone?
Flooding can occur outside high-risk zones. Your location, elevation, drainage, prior losses, mortgage requirements, and comfort with out-of-pocket risk should all be considered.
Can I buy flood insurance right before a storm?
Do not count on it. Most NFIP policies have a 30-day waiting period, so it is best to arrange coverage well before a storm threat develops.
How can I find out whether I already have flood coverage?
Review your declarations pages or ask your insurance agent to confirm whether you have a separate flood policy, who issued it, and what building and contents limits apply.
Not sure if you have flood coverage? Call Harris General Insurance Agency at 504-353-1535 in Kenner. A real person answers every call, Monday through Friday.